5 Options For Purchasing A Property Without A Deposit (Ep216)
Originally recorded in August 2014. Figures and rules mentioned reflect the market at the time.
You can purchase a property without a deposit in Australia. In this article I’m answering a question from Tracy, who asked: “Are there any options for investing in property without a deposit, just a plain weekly or monthly payment?” Here are five options if you want to purchase a property with zero deposit.
Key takeaways
- There are ways to buy with no deposit, but they’re tricky, and whether some of them are legal depends on your state.
- Owner finance, where the seller acts as your lender, is more common and probably the safer of the two main options.
- Lease to buy mostly benefits the seller: if you default, you lose the extra rent you’ve paid.
- Property options and long settlements with early access rely on the property going up in value and finding a lender who’ll accept that equity as your deposit.
- Guarantor (family pledge) loans let you borrow 100%, with someone guaranteeing part of the loan.
The two main options
Now Tracy, there are options out there, but they’re… what’s the best word? Tricky, I guess. The two major options are owner finance and lease to buy.
Depending on what state you’re in, it depends on whether or not they’re actually legal. I think owner finance is legal in South Australia, but you need to check what’s legal in your particular state.
Let’s look at owner finance first, because that’s more common and it’s probably the safer thing to do.
Option 1: Owner finance
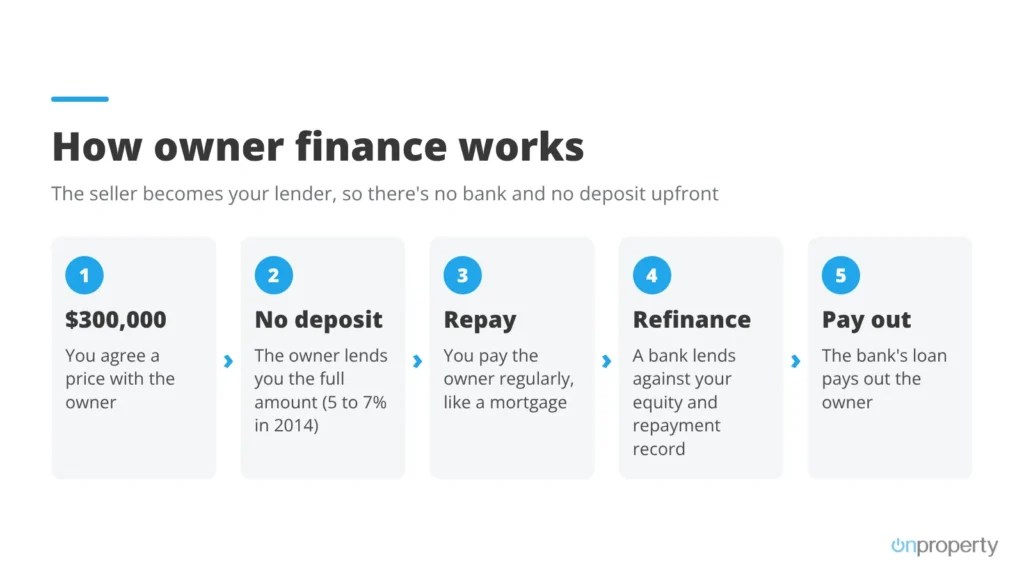
Owner finance is when, rather than going to the bank or a lender, getting a loan, receiving that loan in cash and giving that cash to someone to buy their property, you get rid of the lender altogether. You talk to the owner of the property and the owner extends a loan to you.
Let’s say a property is worth $300,000. You might say to the owner, “I’ll buy it off you, but rather than paying anything upfront, I’m going to assume a loan with you of $300,000 at 7%” (or 6%, or 5%, whatever). You can negotiate; you can make it what you want it to be.
You draw up contracts and do all the legal stuff so that it’s legal, and then you take ownership of the house. I’m pretty sure the title will remain with the original owner because you haven’t fully paid them, the same way the title remains with the bank or lender until you fully pay it off.
Basically, you treat the old owner as your lender. You pay them on a consistent basis, you pay your mortgage, and eventually you’ll either pay them off, or (what most people do) after a couple of years you go to a traditional lender and say, “Hey, look, I’ve got this property, I’ve been paying my mortgage on time, and I’ve got some equity because the property’s gone up in value. How about you give me a regular loan?”
The bank looks at you and goes, “Look at this, you’ve been paying on time, you’re awesome. I’ll give you a loan.” Then you take that lump sum and pay out the original owner.
So that’s owner finance in a nutshell.
Finding an owner finance property
In a fast-moving market, finding someone who’s willing to do owner finance isn’t super easy. There are companies out there that do owner finance as their business, so you could potentially look at one of those. I’d simply go into Google and search “owner finance properties” or something like that.
But you’re going to be extremely limited in what properties you can buy.
Option 2: Lease to buy
The other method is lease to buy. You take on a lease on the property and go in and live in it. You haven’t purchased the property, but you’re paying extra rent.
| Per week | |
|---|---|
| Normal market rent | $400 |
| Extra going towards your deposit | $200 |
| Total you pay | $600 |
Once you’ve lived there long enough and built up that deposit, you then have the option to buy the property.
Why I’m wary of lease to buy
Everything I’ve heard about these lease-to-own properties is that they really benefit the person selling, because so many people default and the seller gets to keep the extra money.
You’re paying extra rent, and if you have to default, you have no way of getting that extra money back, because it’s just security on that one property. It’s not money sitting in a savings account that you can take anywhere.
Maybe not a lot, but I have heard of some sellers taking advantage of people using this strategy. So just because of what I’ve read, it’s not something I would do.
Why I’d lean towards owner finance
I’d try to negotiate and go down the owner finance road if you can, either by finding a company that does it and will accept no deposit, or by finding a seller who likes the idea of owner finance. Maybe they’re in a desperate situation: their property can’t sell, so they’re willing to accept other offers.
Obviously you’re going to be very limited in what you buy, and if you’re buying from a desperate owner, there may be higher levels of risk associated with that. So you need to do your research first and make sure you understand what type of property you’re getting.
From my knowledge, they’re the two main ways to do it.
Option 3: Property options
Another way to do it (and I’m not actually sure how these work, or if they work) is property options.
You go to someone and say, “I’m going to pay you $1,000 or $2,000 for the option to buy your property at this set price in the next five years.” It’s just like options in stocks, which you may or may not be familiar with. Basically, you have the ability, if you want to exercise that option, to buy the property at that price.
What could happen is the property goes up in value beyond the price you have the option for. That difference between the actual value of the property and your option price may mean you can get a loan without paying a deposit, because the equity becomes your deposit.
But most lenders will value your property at either its value or what you’re paying for it, whichever is lower. So you do need to find a lender who’s going to help you out there.
Option 4: A long settlement with early access
The other thing you could do (and again, you’d need to find a lender you could do this with) is agree to buy a property but with a long settlement period. Maybe it’s three months, maybe it’s six months, and you get a clause in for early access to the property.
So maybe you’d sign off on a dilapidated property, get early access to it, then go in and do all the renovations using your own money. You’d then get the property revalued before settlement.
Hopefully the property’s gone up in value, and you’d then need to find a lender that would accept the equity as your deposit.
Option 5: Guarantor loans
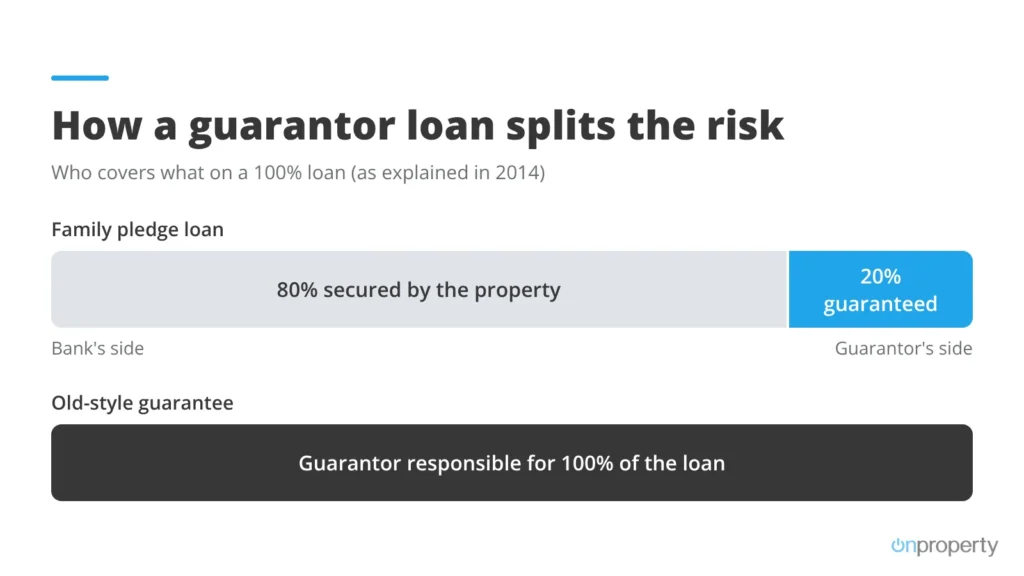
So that’s four ways I know of. Actually, there’s one more, and that’s guarantor loans. Banks now have these family pledge loans, which allow you to purchase a property without a deposit.
Let’s say you have no deposit at all. The banks will give you a 100% loan as long as you’ve got someone to come in as your guarantor.
What makes guarantor loans different from the past is that the guarantor used to be responsible for 100% of your loan if you defaulted and disappeared. Now they’re only responsible for the portion above the 80% loan to value ratio (LVR).
You take responsibility for all of it, but if you disappear and don’t pay, they’re responsible for the 20%, and the bank, I guess, becomes responsible for the other 80%. That’s good, because it means they’ve got limited liability in the situation.
Then you can get your property revalued at a later date, and if the property’s gone up in value or you’ve paid it down, you can get the guarantor removed from the property.
It’s possible, but it’s not easy
So there you have five different ways you can potentially purchase a property without a deposit. It’s not easy. You’re either going to need to do the hard work with options or owner finance to find a property that’s suitable, or you’re going to need someone to vouch for you through a guarantor loan or something like that.
I hope this has helped answer your question, Tracy.
Remember, your long-term success is only achieved one day at a time.
Related articles
- 7 Ways To Buy A House Without A Deposit
- How To Buy A House With A Small Deposit
- Lender’s Mortgage Insurance Explained